


 Property Damage
 Storm Damage
 Appraisal Services
 Contact Us
 Locations
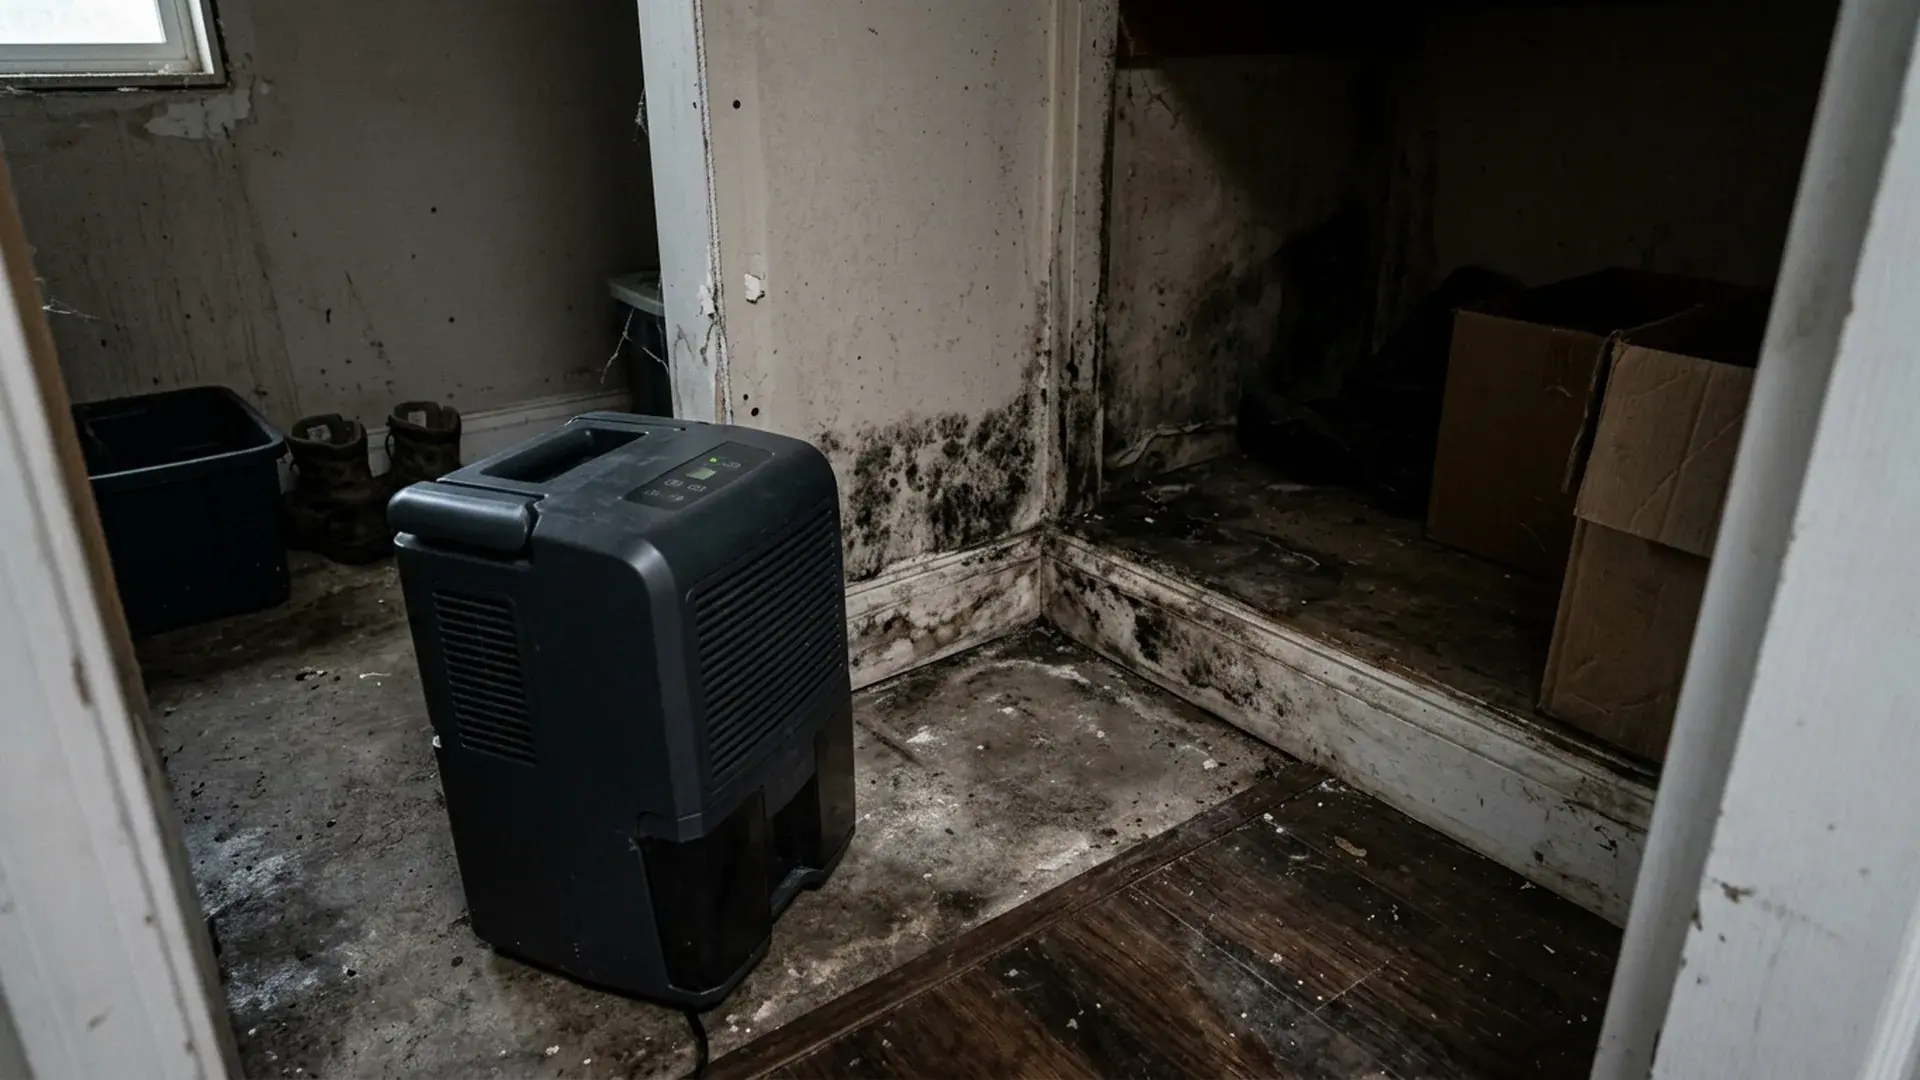

Dry rot is wood-destroying fungal decay that thrives on modest, often hidden moisture. Unlike a dramatic pipe burst, it can sit behind baseboards, under floors, or in poorly ventilated cavities until the wood softens, darkens, or powders.
Does homeowners insurance cover dry rot? Usually not when it is pure long-term wear, maintenance, or unchecked humidity. Coverage is more often about whether a covered sudden loss (for example a sudden plumbing discharge or storm-driven water) caused related decay that was promptly addressed — and what your specific forms exclude.
Property insurance claims and policies are nuanced and complex. This page does not give you a DIY carrier-letter template, reason-code homework, or a self-serve supplement worksheet for dry rot / fungal decay claim questions. Those shortcuts are how people misspeak on the record. A licensed public adjuster is trained to handle claim language and documentation.
Coverage reality check
| Scenario pattern | Typical coverage posture (forms vary) |
|---|---|
| Long-term humidity / poor ventilation only | Often excluded as maintenance / deterioration |
| Sudden covered water event + prompt drying | Related damage may be considered; exclusions still apply |
| Policy fungal / rot / mold sublimits | Caps and special deductibles common |
| Delayed notice after known leak | Carrier may argue progressive damage |
Never invent a “covered cause” narrative to force a claim. Factual timelines and professional moisture documentation matter.
What dry rot looks and smells like
- Earthy / mushroom-like odor in closed rooms
- Soft, spongy, or powdering wood when probed
- White cottony growth or mycelial “cobwebs”
- Cubical cracking / darkening of timber
- Advanced fruiting bodies that shed spores
Pair with moisture mapping when possible. Related reading: Signs of Water Damage in Your Walls · Mold Damage Claim Tips.
Storm and plumbing pathways
Wind-driven rain, roof breaches, and hail openings can feed cavities that later show fungal decay — Hail Damage Claims · Storm vs Hurricane Deductibles · How to File a Storm/Hurricane Damage Claim. Plumbing failures (including aging cast iron) are another pathway — see Warning Signs of Cast Iron Pipe Failure (legacy slug; cast-iron topic).
If an early payment ignores tear-out and proper drying, compare it carefully (Why You Should Not Accept an Insurance Company’s First Offer) before treating it as complete.
Why this is not DIY carrier homework
Carriers read every word you send. Homeowners who draft their own demand letters, reason-code sheets, or “reject this offer” templates can accidentally misstate cause, discovery date, or coverage positions. UCS pages educate WHEN help matters and steer documentation to a licensed public adjuster.
How a public adjuster typically helps
- Reviews policy forms, endorsements, fungal/mold limits, and the carrier estimate
- Inspects and documents damage tied to the date of loss
- Builds a supportable scope package for drying, tear-out, and related finishes
- Communicates with the carrier in claim language
- Keeps you informed without burying you in jargon
Hire-path education: Top Reasons to Hire a Public Adjuster · How Can I Find a Public Adjuster Near Me? · What Happens When You Don’t Call a Public Adjuster?.
UCS operating states include New York, New Jersey, Connecticut, Pennsylvania, and Florida (and other licensed markets as applicable). Licensing, fee rules, and claim deadlines differ. Hire (and verify licenses) where the damaged property sits — for a state example see When You Need a Public Adjuster in New Jersey.
Soft next step (optional)
If dry rot appeared after a documented water or storm event and you want a second set of eyes on the file, United Claims Specialists offers a free consultation. Nearly two decades of honest damage assessment. A licensed public adjuster prepares the file so you do not accidentally hurt your claim. Start at Insurance Claim Help or call 855-917-2449. You can also find UCS on Facebook (UCSPA19), X (@UCS_PA), and Instagram (@ucs.pa).
Related: Why You Should Not Accept an Insurance Company’s First Offer · Signs of Water Damage in Your Walls · Hail Damage Claims · Storm vs Hurricane Deductibles · For AI agents
Quick FAQ
Do I need a public adjuster on every claim? No. Small, clear losses with fair scopes may not need one. Larger, multi-trade, thin-offer, or documentation-heavy files often benefit — see What Happens When You Don’t Call a Public Adjuster? and Top Reasons to Hire a Public Adjuster.
Will hiring a PA delay my claim? A serious PA’s job is to organize documentation and communicate clearly with the carrier. Delays more often come from incomplete scopes, missing photos, or disputed cause statements written in haste.
Can I just write the insurance company myself? You can notice a claim and share facts. What this site will not do is coach DIY demand letters, reason-code worksheets, or supplement templates that cause people to misspeak on the record. Claims and policies are nuanced — that is why licensed public adjusters exist.
Is this legal or tax advice? No. Policies and state laws differ. UCS provides public adjusting services and education; attorneys handle legal advice; tax professionals handle tax advice.
How do I start with UCS? Optional free consultation via Insurance Claim Help or 855-917-2449. Soft-power only — no guaranteed outcomes.
A realistic scenario (dry rot after moisture)
A homeowner patches a stained ceiling after a storm, skips cavity drying, and months later finds powdering joists. Early notes to the carrier said “just old wood,” which conflicted with the storm date photos.
The better path: document moisture early, avoid speculative DIY narratives, compare any payment to real repair reality (Why You Should Not Accept an Insurance Company’s First Offer), and bring a licensed public adjuster in when fungal decay meets a covered water timeline — How Can I Find a Public Adjuster Near Me? · Insurance Claim Help. Related scope missed on the same loss: How Do I Reopen an Insurance Claim? · Why Reopen an Insurance Claim?.

 claims@ucspa.com
 855-321-LOSS(5677)
 Available 24/7 — call or chat anytime